How to Improve CIBIL Score: Practical Steps to Boost Your Credit Rating in India
Learn how to improve CIBIL score with proven tips. Discover free ways to check your score, what a good CIBIL score means, reasons it drops, and steps to reach 750+ for better loan approvals.
-
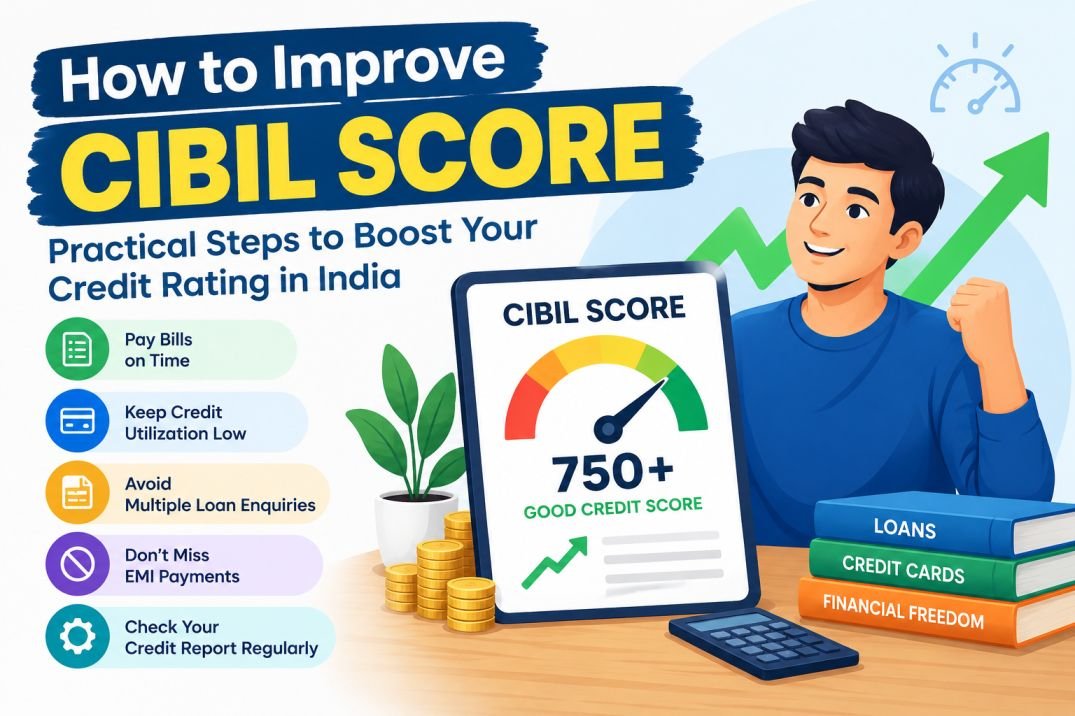
A strong CIBIL score opens doors to loans, credit cards, and better interest rates. Many people in India struggle with a low score and wonder how to improve CIBIL score or how to increase credit score without falling for quick-fix myths. This guide explains the facts clearly so you can take practical steps that actually work over time.
-
What is a CIBIL Score?
A CIBIL score is a three-digit number between 300 and 900 that reflects how you have managed credit in the past. TransUnion CIBIL, one of India’s four major credit information companies, calculates it using data shared by banks, NBFCs, and other lenders. The score looks at your repayment history, outstanding balances, length of credit accounts, types of credit used, and recent loan or card applications.
Lenders use this number as a quick indicator of risk. A higher score suggests you are more likely to repay on time. The score is not permanent. It changes as new information is reported, usually every month or so when lenders update their data. Checking your own score does not lower it because that is considered a soft enquiry. Hard enquiries happen only when a lender pulls your report while assessing a new application.
Understanding the score helps you see why certain habits matter more than others. Payment history carries the heaviest weight. Credit utilisation — how much of your available limit you use — comes next. Older accounts that you manage well also help because they show a longer track record. Too many recent applications or a sudden jump in debt can pull the number down. The system is designed to reward consistent, responsible behaviour rather than one-time actions.
Many people confuse the CIBIL score with the full credit report. The score is the summary number. The report contains the detailed history of accounts, payment status, and enquiries that feed into the calculation. Both matter. If the report has mistakes, the score can be unfairly low even if your actual behaviour has been good. That is why reviewing the full report regularly is as important as knowing the number itself.
-
What Does a 300–900 Credit Score Mean?
The CIBIL scale runs from 300 to 900. Broadly, scores fall into these practical bands used by most lenders:
300–549: Poor. Approval for unsecured credit is difficult.
550–649: Fair. Limited options, higher interest rates if approved.
650–749: Good to average. Many products are accessible, though rates may not be the best.
750–900: Very good to excellent. Strongest chance of approval and competitive terms.
A score of 750 or above is widely treated as a good CIBIL score. It signals low risk and often qualifies borrowers for lower interest rates on personal loans, home loans, and premium credit cards. Scores between 700 and 749 are still workable for most banks, especially if income and existing obligations look healthy. Below 650, many traditional banks become cautious and NBFCs or digital lenders become more common options, usually at higher rates.
What is a good CIBIL score also depends on the product. For a personal loan, many public-sector banks prefer 720–750 or higher for the best terms, while some private banks and NBFCs may consider applications from 650–700. The exact cut-off is never published as a rigid rule because lenders also weigh income stability, existing EMI burden (FOIR), and overall profile. Still, aiming for 750 gives the widest choice and strongest negotiating position.
A score near 900 is possible but rare. Most people with excellent credit sit comfortably in the 750–850 range. Chasing the absolute top number is less useful than building habits that keep you above the thresholds lenders care about.
-
How to Check Your Credit Score for Free
You can check CIBIL score free once every calendar year directly from the official TransUnion CIBIL website. This is a right under RBI guidelines. Visit cibil.com, look for the free score and report option, enter your name, PAN, date of birth, and mobile number, and verify with OTP. The process usually takes a few minutes and gives you both the score and a detailed report.
Many banks also show your CIBIL score inside their mobile apps at no cost. SBI YONO, HDFC, ICICI iMobile, Axis, and Kotak apps are common examples. Some UPI apps and fintech platforms such as Paisabazaar offer free monthly updates of scores from multiple bureaus. These soft checks do not affect your score.
It is wise to pull the official free report at least once a year and review it carefully. Look for accounts you do not recognise, wrong payment statuses, closed loans still shown as active, or incorrect personal details. Keep a record of the report so you can compare changes later. Avoid random websites that ask for excessive personal or income details under the name of a “free check” — many are lead generators rather than genuine score services.
Checking regularly helps you catch problems early and track whether your efforts to improve the score are working.
-
7 Common Reasons Your Score Drops
A sudden drop often leaves people asking why did my CIBIL score drop. The most common causes are straightforward:
Missed or late payments on loans or credit cards. Even one 30-day delay can leave a mark that stays for years.
High credit utilisation. Using more than 30–40% of your total card limits signals higher risk.
Multiple hard enquiries in a short period. Applying for several loans or cards at once looks like you are hunting for credit urgently.
Settled or written-off accounts. Paying less than the full amount and getting a “settled” status is better than default but still hurts more than full repayment.
Errors in the report — wrong balances, duplicate accounts, or accounts that belong to someone else.
Closing old credit cards that had a long positive history, which shortens the average age of your accounts.
Becoming a guarantor for a loan that later turns delinquent.
Other factors include a sudden large increase in outstanding debt relative to income or new unsecured credit piled on top of existing obligations. The good news is that most of these issues can be addressed with time and consistent action. The score recovers as positive information outweighs the older negatives.
-
10 Practical Ways to Improve It
Here is how to improve CIBIL score and how to improve credit score using credit card and other tools in a realistic way:
Pay every EMI and credit card bill on or before the due date. Set auto-debit or calendar reminders. Payment history is the single biggest factor.
Keep overall credit utilisation below 30%. If your total limit is ₹1 lakh, try to keep outstanding balances under ₹30,000. Pay down balances before the statement date when possible.
Avoid closing old credit cards that you manage well. Older accounts lengthen your credit history and increase total available limit, which can lower utilisation.
Dispute incorrect entries promptly. Raise the issue with CIBIL and the lender, attaching proof such as payment receipts or closure letters. Corrections can lift the score once the report is updated.
Limit new credit applications. Space them out and apply only when you genuinely need the product.
Maintain a healthy mix of secured (home or car loan) and unsecured (personal loan or cards) credit if it fits your situation.
If you have overdue amounts, clear them in full rather than settling for less whenever possible. Ask for a clearance letter after payment.
Consider a secured credit card against a fixed deposit if you have little or no credit history. Use it lightly and repay in full each month.
Request a credit limit increase on existing cards only if your spending stays the same. A higher limit with the same balance improves the utilisation ratio.
Review your full credit report from all four bureaus once a year and keep personal details consistent across lenders.
These steps work together. How to get a 750 credit score is rarely about one dramatic action. It is about months of on-time payments, controlled spending on cards, and a clean report. CIBIL score required for personal loan is often lower at NBFCs, but 750 still opens the best rates at major banks.
-
How Long It Takes to Improve a Score
There is no fixed timeline or guaranteed jump. Positive changes usually begin to appear after 3–6 months of consistent on-time payments and lower utilisation. Larger improvements, especially recovering from past delays or high balances, often take 6–12 months or longer. Old negative marks gradually lose weight as newer positive history builds, but they do not disappear overnight.
RBI has pushed for more frequent data updates from lenders, which can help recent good behaviour show up sooner. Still, patience and consistency matter more than any single tactic. Anyone promising a big jump in weeks is not following how the system actually works.
Frequently Asked Questions
My main purpose in writing these posts is simply to help you. All the information shared here is carefully put together just to be useful for your daily needs. I always try my absolute best to provide the right guidance and support you as much as possible.


Comments (0)